
For the first time in three years, the Bank of Canada has increased its key policy rate, signaling that mortgage rates are set to change for many Canadians.
On Wednesday, the central bank elevated its benchmark interest rate by 25 basis points to 2.5 percent. Bank of Canada Governor Tiff Macklem indicated that further increases might occur if inflation, primarily driven by rising fuel prices, continues in the upcoming months.
In response to Wednesday’s announcement, Canada’s largest banks have already begun to raise their prime interest rates. All five major banks increased their prime rates by 25 basis points to 4.70 percent, which is the rate provided to their most creditworthy borrowers.
-
Bank of Canada governor states that the rate increase to 2.5% was necessary due to ongoing inflation
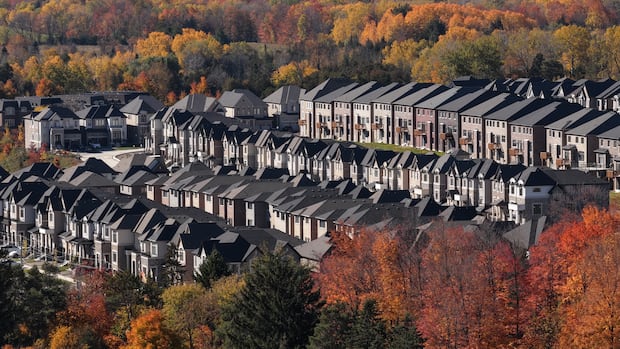
Variable rate mortgages will be the first to adjust, as these are directly tied to the prime rate set by the issuing bank.
Meanwhile, rates for new fixed mortgages are influenced by the bond market. When a central bank raises interest rates, new bonds offer improved returns. As investors seek higher yields, lenders respond by increasing mortgage rates to protect their profit margins.
“In an environment where rates are rising, deciding between fixed and variable can be quite difficult. While variable rates are lower and offer flexibility, it’s important to budget for potential future rate hikes,” said Clay Jarvis, a mortgage specialist at Ratehub.ca, in a press release following the rate announcement on Wednesday.
“Though fixed rates are high, the mortgage costs are locked in once you qualify. This kind of predictability can justify paying a higher rate,” he added.
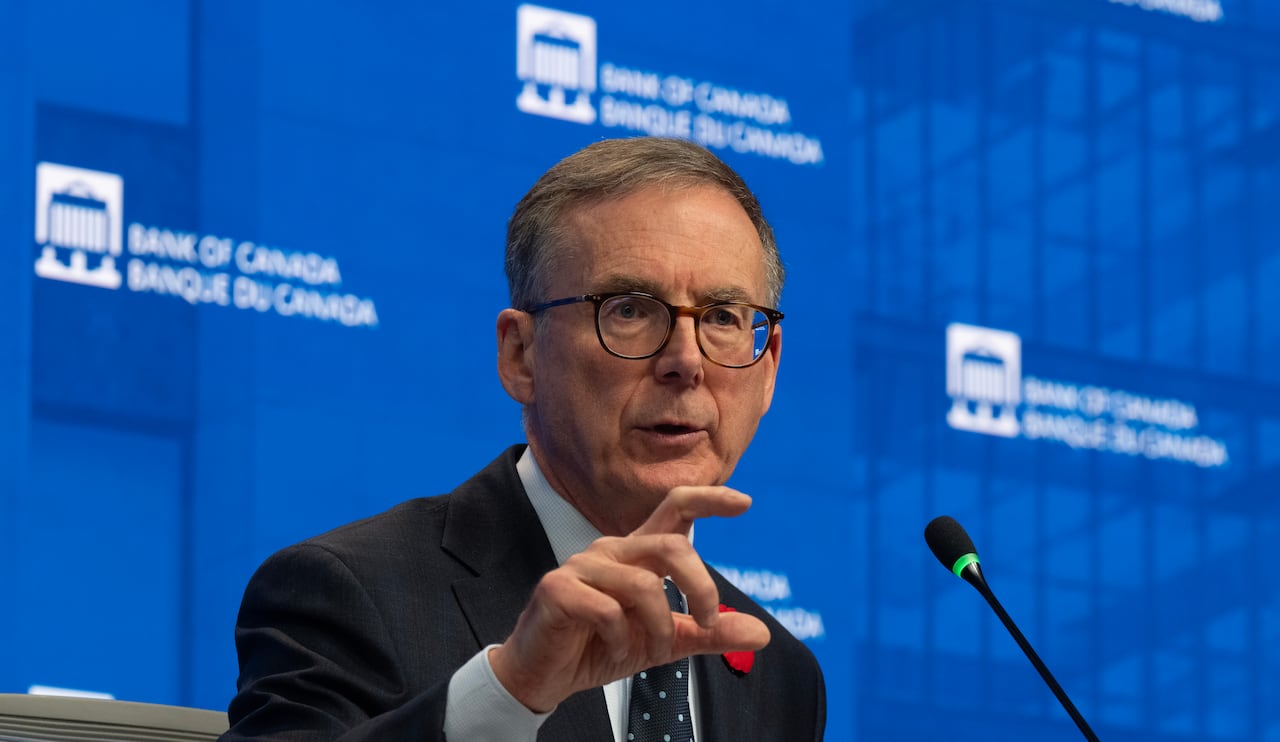
Bank of Canada Governor Tiff Macklem addresses reporters during a news conference in Ottawa on Wednesday, where the governing council decided to increase interest rates by a quarter percent. (Adrian Wyld/The Canadian Press)
During a press briefing in Ottawa on Wednesday, Macklem recognized that rising interest rates may be challenging for many Canadians and businesses.
“We understand this,” he stated. “The immediate impact may not be pleasant, but this is how we bring inflation down, which will ultimately benefit Canadians and businesses alike.”
Variable rate mortgage holders will be affected the most
The Bank of Canada’s initial rate increase since July 2023 will be felt right away by those with variable rate mortgages. Broker Marcus Tzaferis, based in Toronto, believes this adjustment could be substantial.
For a $500,000 mortgage, a rate increase of 25 basis points would result in an average monthly payment increase of approximately $70. While it may seem minor, Tzaferis pointed out, “For a consumer already facing financial strain, these incremental increases will have a significant impact.”
The central bank has also indicated that additional rate hikes may be forthcoming — if the bank were to raise rates by another 50 or 75 basis points, Tzaferis noted, “It’s easy to see how that would affect people’s monthly budgets.”
Given that rate hikes were anticipated, Tzaferis mentioned that he has been receiving inquiries from Canadians looking to explore their options.
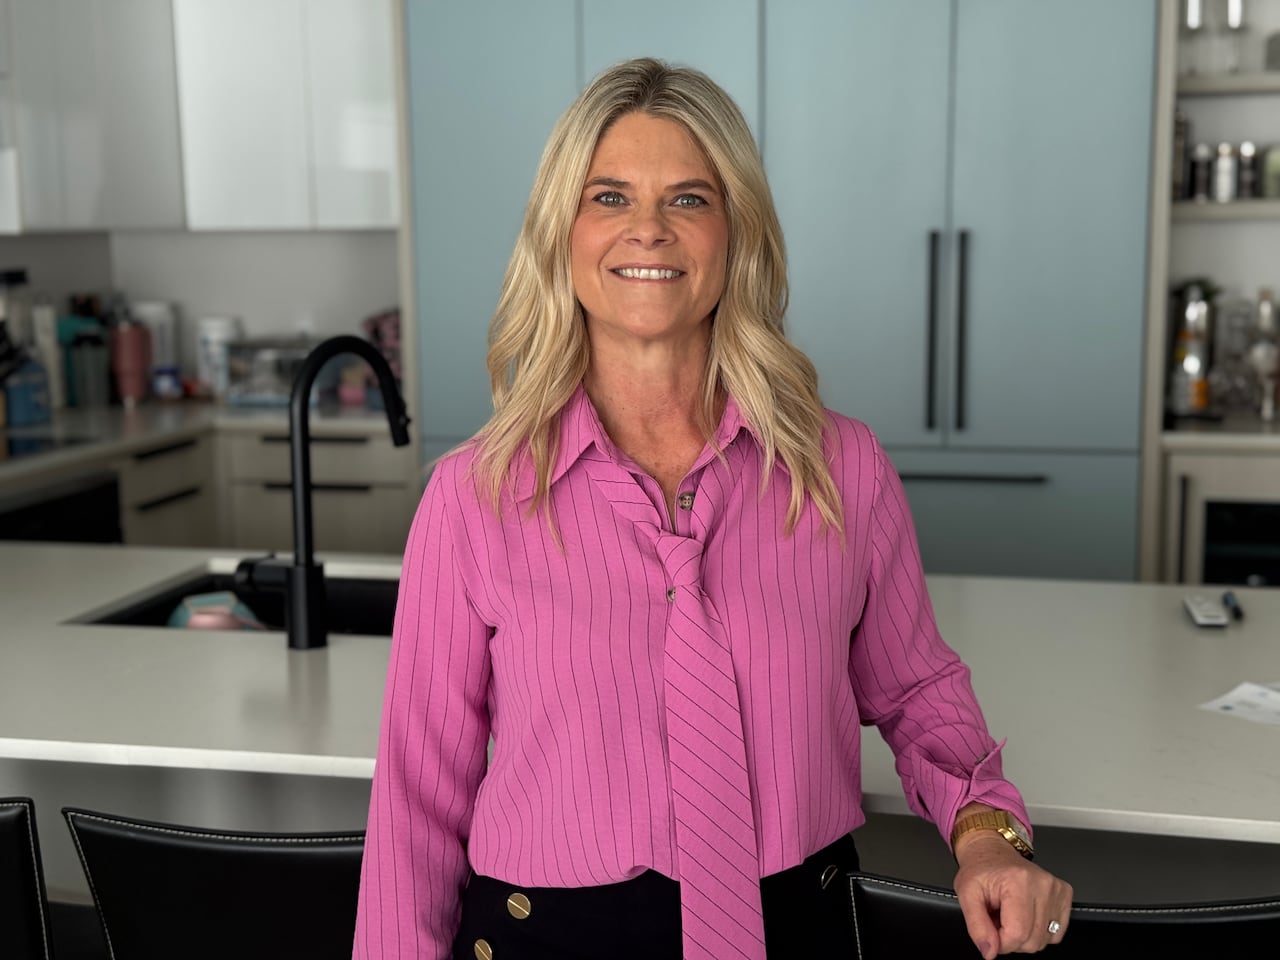
Barbara Best stands in the kitchen of her Toronto condo on Wednesday. She recently transitioned from a variable to a fixed rate mortgage and believes the increased cost is justified for the peace of mind it provides. (Laura MacNaughton/CBC)
For instance, Barbara Best has held a variable rate mortgage on her Toronto condo since 2022 — the same year the Bank of Canada initiated a prolonged rate hike cycle — but she recently opted to switch to a fixed rate well before her mortgage was due for renewal.
Even though fixed rates are now significantly higher than variable ones, she acknowledges that her monthly payments have increased considerably, yet she believes it’s worthwhile.
“It was a noticeable rise in payment, but it affords me certainty. It grants me peace of mind,” Best remarked.
Tzaferis advises that “this is the moment” to consider obtaining a fixed-rate mortgage if borrowers wish to exit a variable mortgage or their mortgage is approaching renewal.
“The most critical step is for Canadians to start the renewal process early,” Tzaferis emphasized. He suggested that being informed about the best available rates and initiating discussions with an advisor could aid consumers in making well-informed decisions.
Rate increase may dampen housing market further
This rate increase is also likely to exacerbate the already sluggish housing market.
Deputy Governor Carolyn Rogers stated that Canada’s housing market is experiencing challenges, especially in Ontario and British Columbia, and this rate hike will intensify those difficulties.
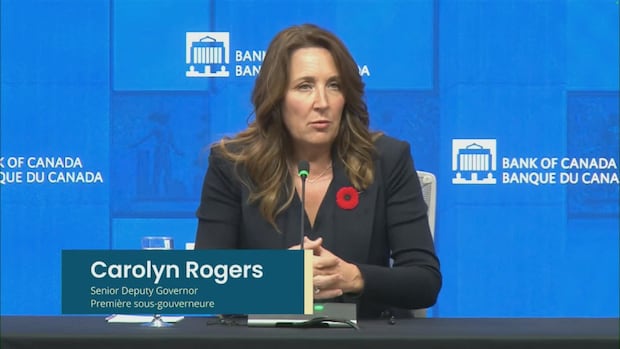
Bank of Canada senior deputy governor Carolyn Rogers noted after the interest rate hike that the bank’s outlook for housing is ‘pretty subdued’ due to various factors, including economic uncertainty.
Wednesday’s increase reduces the pool of potential buyers, shifting leverage from sellers to those able to secure the necessary financing for purchases. This could lead to a further decline in home prices.
Earlier this month, the Canadian Real Estate Association (CREA) adjusted its 2026 home sales forecast downward for the third time this year.
Joel Fox, chief operating officer of the Toronto-based real estate law platform Ownright, concurs that Wednesday’s rate increase will contribute to the negative sentiment in the housing market.
“A rate hike is likely to result in year-over-year declines in housing activity for the remainder of this year and into the next, and I don’t foresee any turnaround unless rates drop,” he stated after the rate decision on Wednesday.
“The market was already in a difficult place, and it’s hard to envision it declining much further,” he added.